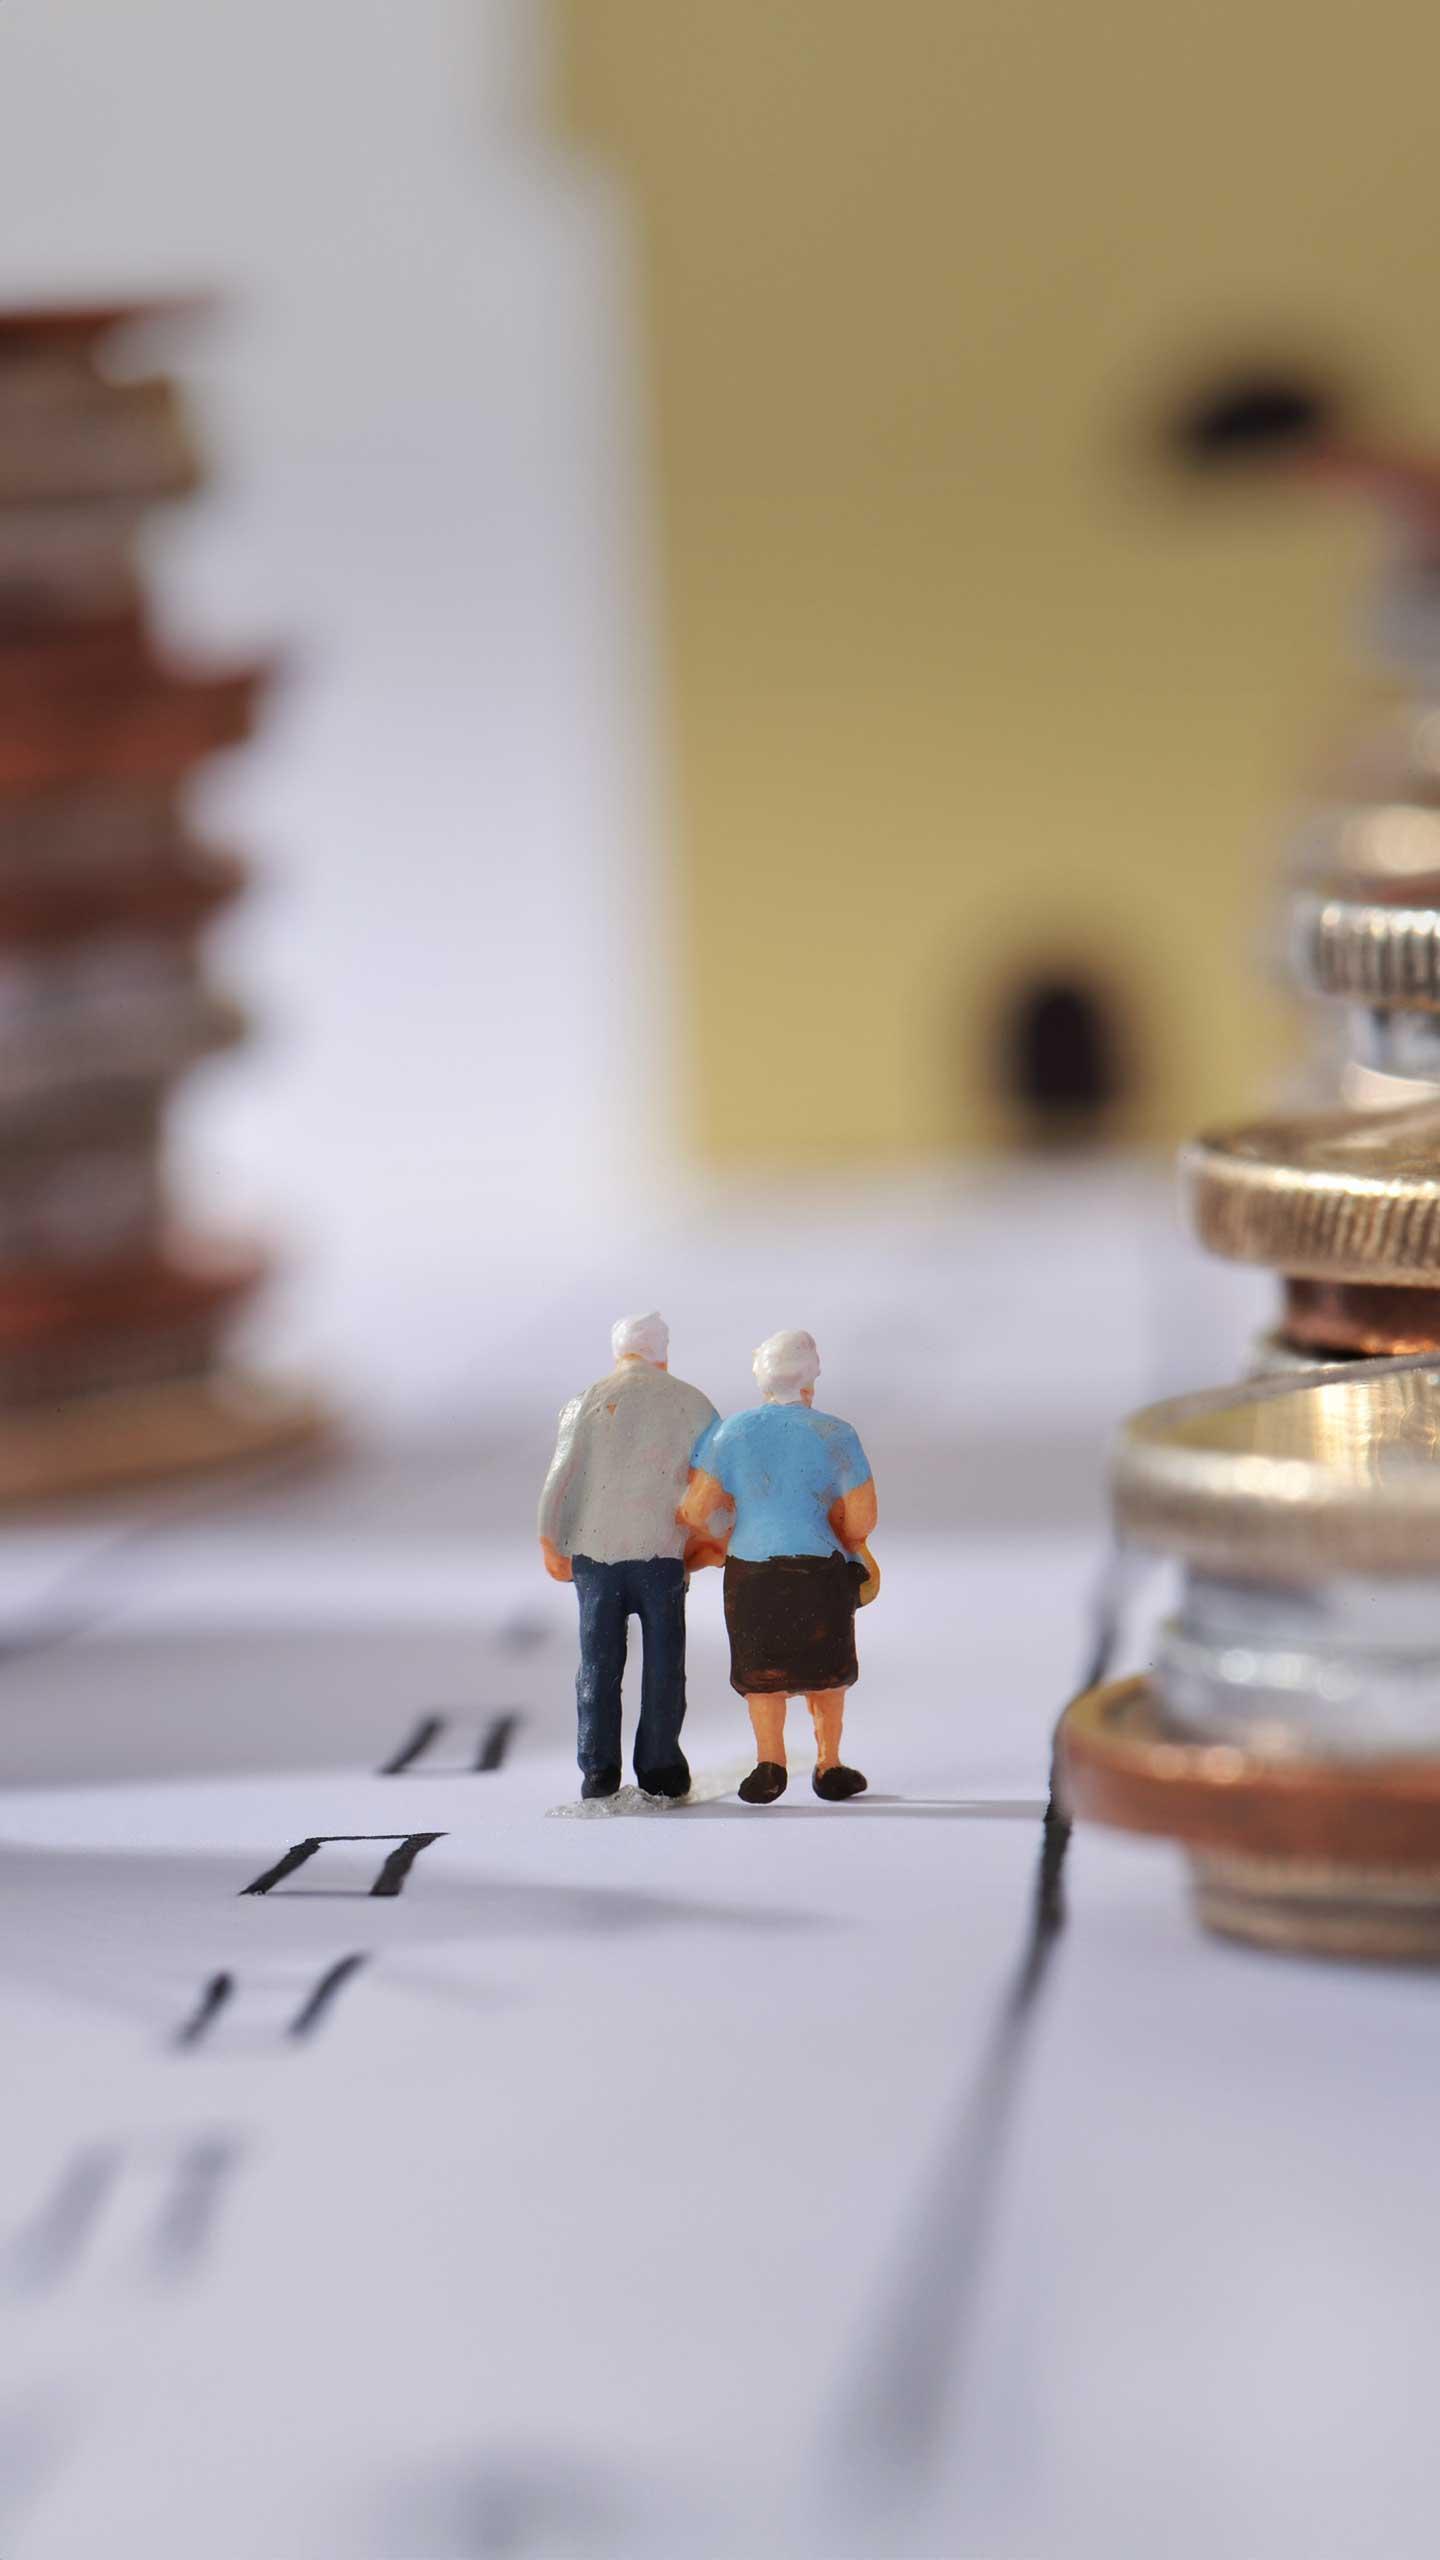
Higher-Income Individuals Face Evolving Retirement Planning Landscape, Requiring Strategic Integration with Broader Financial Goals
What's Happening?
Retirement planning for higher-income individuals is shifting from a simple savings approach to a more integrated and strategic process. As income levels rise, the focus expands beyond merely contributing
more money to considering how retirement plans intersect with tax planning, investment strategy, business planning, estate planning, cash flow management, and long-term wealth preservation. Decisions in one area, such as increasing retirement contributions, can impact others, like available cash for business investments. This necessitates a holistic view where current financial objectives and future security are considered together. Income thresholds and tax implications also influence available retirement strategies, with some accounts having income-based eligibility rules or contribution limits. Business owners, in particular, have additional planning opportunities and must ensure their retirement strategies evolve with their business growth and profitability. The emphasis is on strategic planning rather than just maximizing contributions, recognizing that a plan effective at lower income levels may no longer be optimal as wealth increases.
Why It's Important?
This evolution in retirement planning is crucial for U.S. industries and individuals as it highlights the increasing complexity of wealth management. For high-income professionals and business owners, understanding these interconnected financial elements can significantly impact their long-term financial security and wealth preservation. Without a coordinated approach, individuals risk suboptimal outcomes, such as inefficient tax strategies or missed opportunities for wealth transfer. The shift underscores the need for specialized financial advisory services that can navigate complex tax laws, investment diversification, and business-specific retirement options. Those who adapt to this strategic planning model stand to gain greater financial flexibility and confidence, while those who continue with a traditional, isolated savings approach may find their retirement goals undermined by unforeseen tax liabilities or insufficient capital preservation. This trend also impacts the financial services industry, driving demand for comprehensive, integrated planning solutions.
What's Next?
Individuals with higher incomes will increasingly need to engage in regular, comprehensive reviews of their retirement strategies, especially following major life or business events such as selling a business, rapid income growth, marriage, or career transitions. Financial advisors will likely see a growing demand for integrated services that combine retirement planning with other financial disciplines like tax and estate planning. The industry may also develop more sophisticated tools and products tailored to the nuanced needs of high-net-worth individuals and business owners, focusing on tax diversification and risk management beyond just investment performance. Furthermore, ongoing changes in tax laws and market fluctuations will necessitate continuous adaptation of retirement strategies, making flexibility a key component of successful long-term planning. The emphasis will be on building resilient plans that can withstand various economic scenarios and personal changes.
Beyond the Headlines
The evolving landscape of retirement planning for higher-income individuals reflects broader societal and economic shifts, including increased longevity, the decline of traditional pensions, and the growing complexity of financial markets. This trend highlights a move away from a one-size-fits-all approach to retirement, emphasizing personalized and dynamic strategies. Ethically, it underscores the responsibility of financial advisors to provide truly holistic and client-centric advice, moving beyond product sales to genuine fiduciary guidance. Culturally, it challenges the traditional notion of retirement as a fixed endpoint, suggesting a more fluid transition where financial decisions are continuously integrated into an individual's life and business trajectory. The long-term implication is a more sophisticated and demanding financial planning environment, where continuous learning and adaptation are essential for both individuals and financial professionals to secure future financial well-being.