Gen Z Navigates Financial Planning Amidst Economic Uncertainty with Focus on Budgeting and Savings
What's Happening?
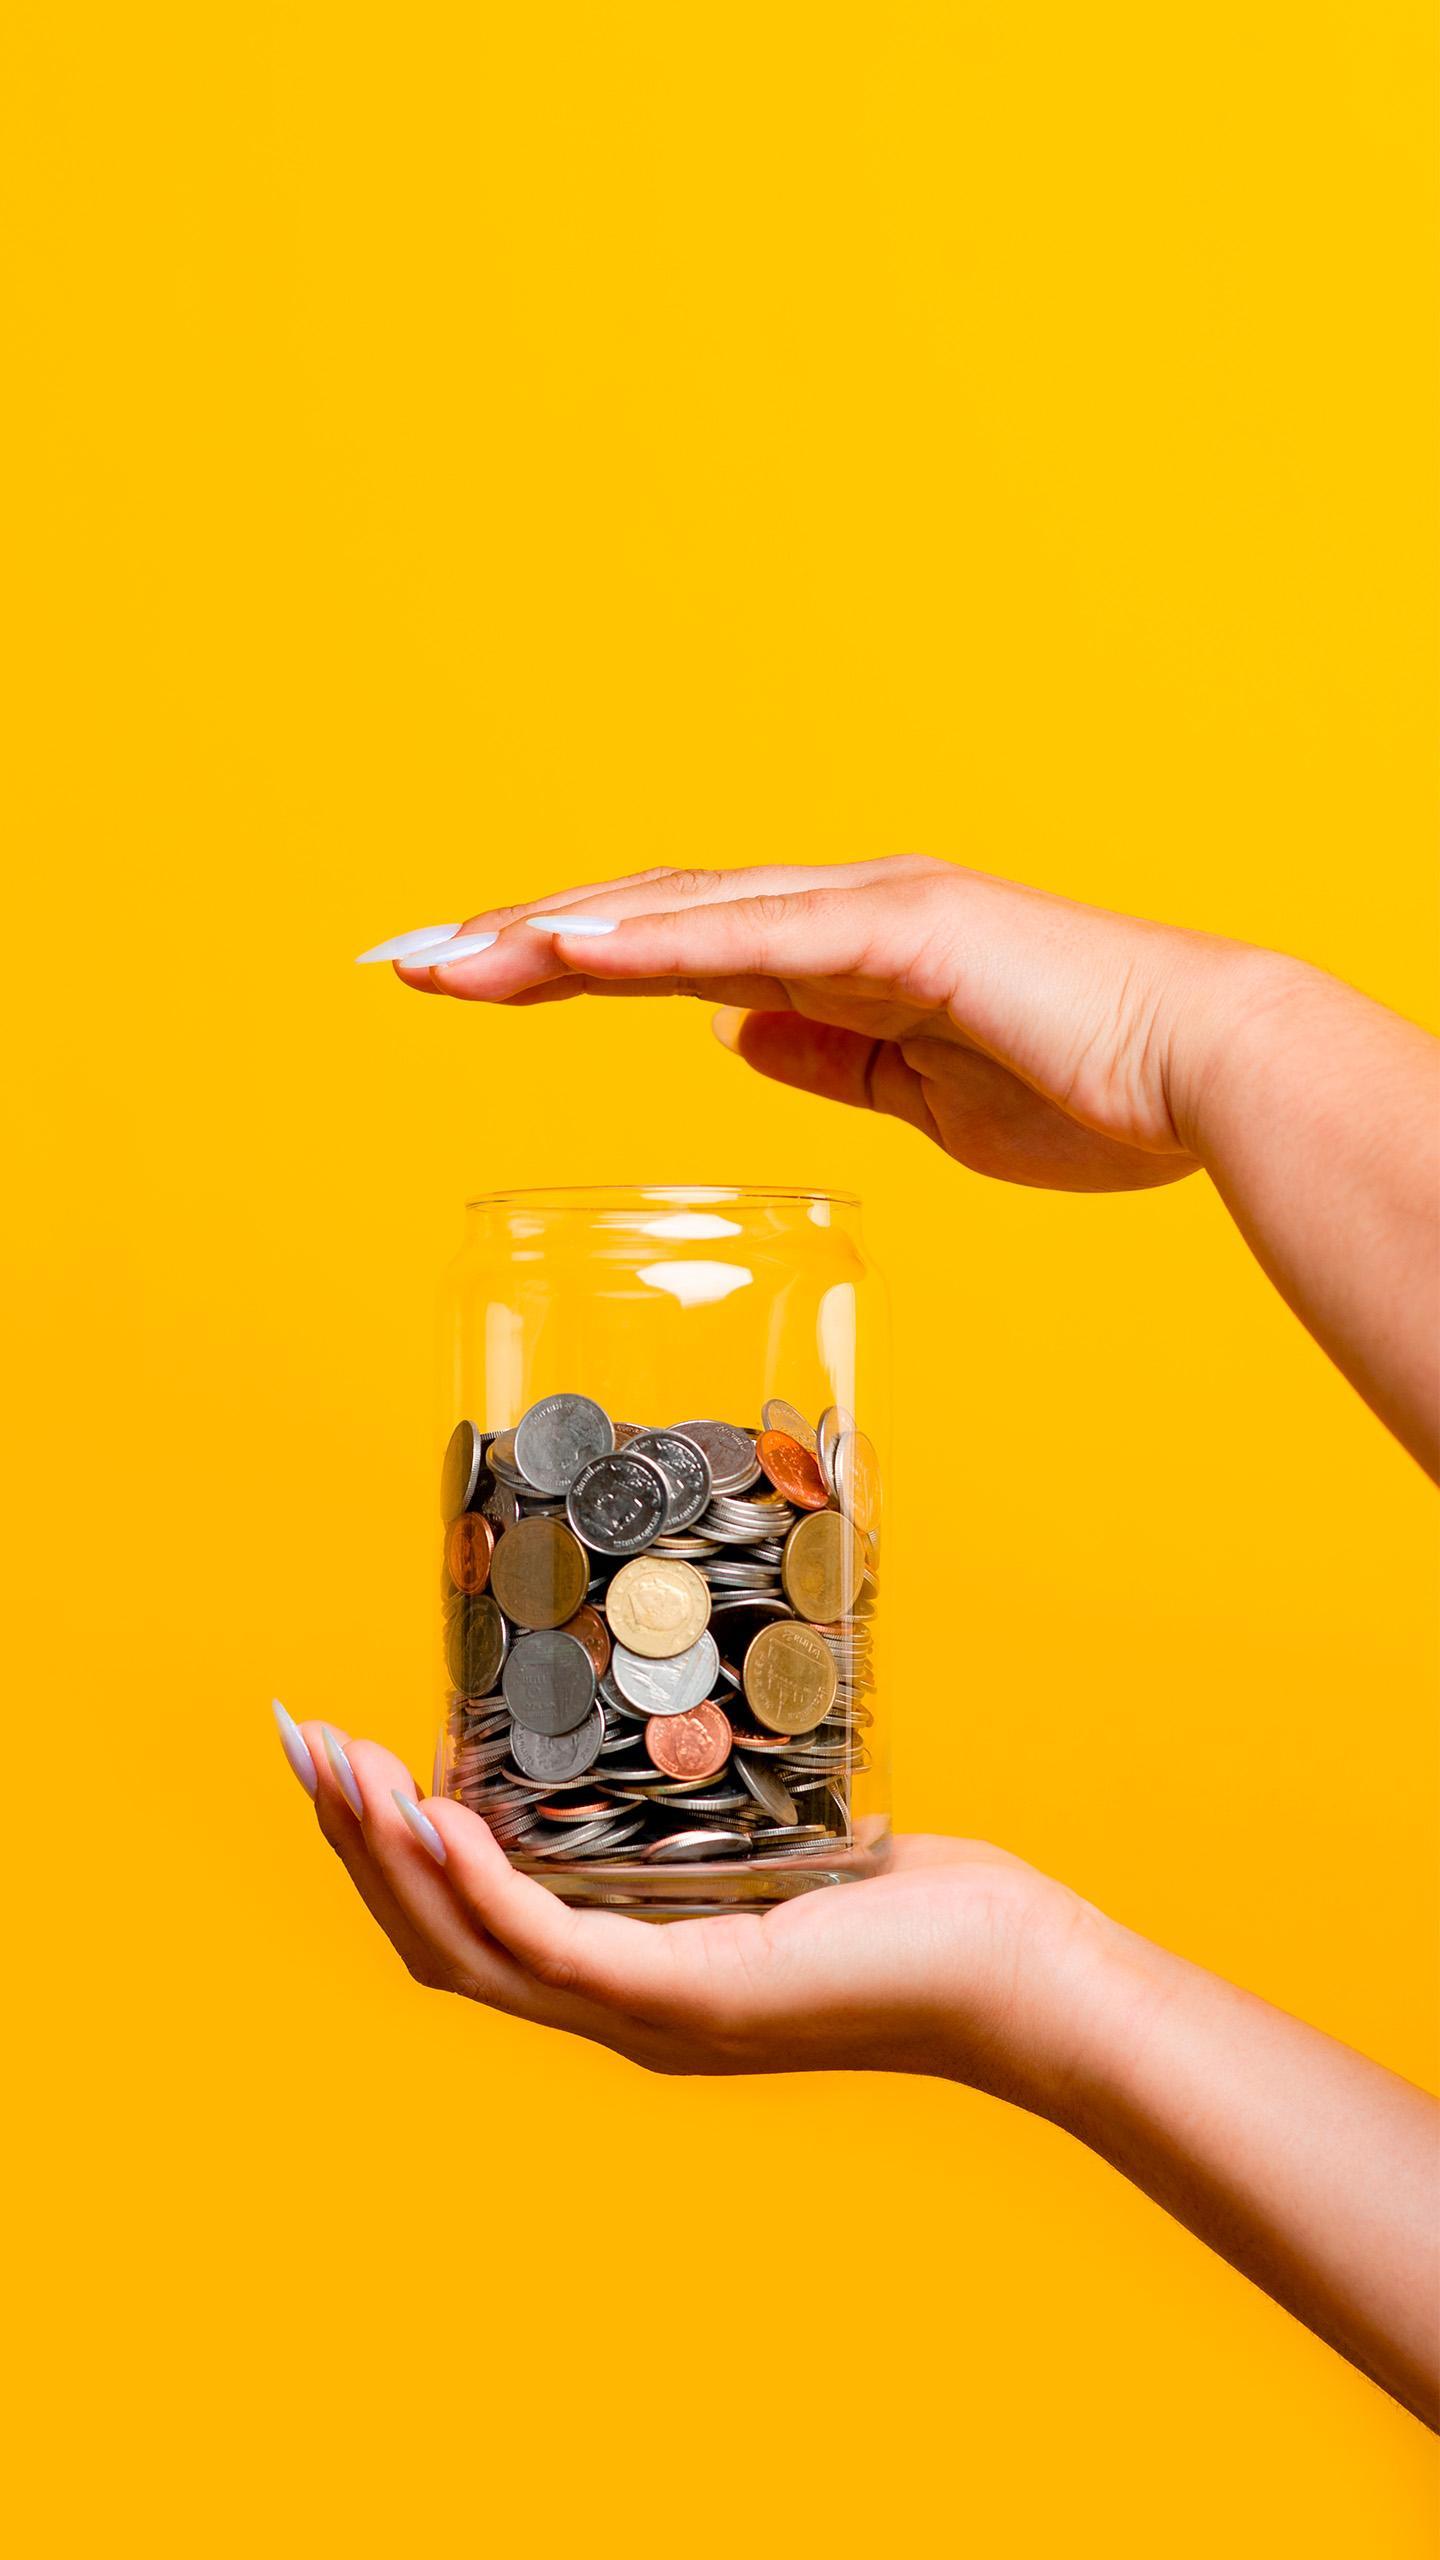
Gen Z faces unique financial challenges, prompting a focus on practical budgeting and saving strategies. Key recommendations for this demographic include creating a detailed budget to track income and expenses,
prioritizing essential needs over discretionary wants, and regularly reviewing financial plans on a monthly basis. A crucial step highlighted is establishing an emergency fund capable of covering three to six months of living expenses before considering investments. To maximize savings, opening high-yield savings accounts is advised due to their potential for better interest accrual. Furthermore, the wise use of credit cards, specifically paying off balances in full each month, is emphasized to avoid high-interest debt and build a strong credit score. The importance of starting early with retirement accounts is also noted, leveraging the power of compound interest for long-term financial growth. These strategies aim to equip Gen Z with the tools to manage their finances effectively in a complex economic landscape.
Why It's Important?
The financial strategies outlined are crucial for Gen Z as they enter an economic environment marked by significant uncertainty, including a global pandemic, record inflation, and a volatile job market. These conditions have made traditional milestones like homeownership and debt repayment seem less attainable, leading many young adults to feel financially pressured. By adopting robust budgeting and saving habits, Gen Z can gain a sense of control over their financial futures, mitigating the impact of external economic forces. Building an emergency fund provides a safety net against unexpected expenses, reducing reliance on high-interest debt. Responsible credit card use is vital for establishing a positive credit history, which is essential for future loans and financial opportunities. Early investment in retirement accounts, despite immediate financial pressures, is critical for long-term wealth accumulation, offering a more secure path than high-risk, short-term investments that some Gen Z individuals are reportedly drawn to due to feelings of being 'financially behind.'
What's Next?
As Gen Z continues to navigate their financial journeys, the emphasis will likely remain on adapting these core financial principles to their evolving circumstances. Financial institutions and educators may need to develop more tailored resources that address the specific anxieties and behaviors of this generation, such as their reported inclination towards risky investments. There could be a continued push for financial literacy programs that highlight the long-term benefits of consistent, disciplined saving and investing over quick wealth schemes. Additionally, as economic conditions shift, Gen Z will need to regularly reassess and adjust their budgets and financial goals. The ongoing dialogue about balancing immediate gratification with future financial security will be critical, encouraging a mindset that allows for both present enjoyment and responsible planning. The adoption of digital budgeting tools and high-yield savings accounts is expected to grow as Gen Z seeks efficient and effective ways to manage their money.
Beyond the Headlines
The financial behaviors and challenges of Gen Z reflect broader societal shifts and economic realities. The reported tendency towards risky investments, such as crypto and sports betting, can be seen as a symptom of 'financial nihilism,' where traditional paths to wealth seem inaccessible, leading to a search for shortcuts. This highlights a deeper psychological impact of economic uncertainty on younger generations. The emphasis on budgeting and saving, therefore, is not just about financial mechanics but also about fostering a sense of agency and hope in a seemingly unpredictable world. The advice to prioritize needs over wants and to use credit wisely also touches upon consumer culture and the pressures of instant gratification. Ultimately, the financial education of Gen Z is about more than just money management; it's about building resilience, making informed decisions, and cultivating a long-term perspective in an era where short-term gains often dominate attention. This generation's financial habits could significantly shape future economic trends and consumer behavior.